What Are Level 2 and Level 3 Interchange Programs?
If your business accepts payments from other businesses, government agencies, or large organizations, you may be paying more in credit card processing fees than…
Accepting credit cards, debit cards, and digital wallets is table stakes now. In the United States, more than 80 percent of in-store transactions and essentially all ecommerce checkouts involve an electronic payment method, not cash.
The cost to accept those payments is called “payment processing,” and it’s one of the top operating expenses for many merchants, often larger than utilities, POS hardware leases, or even marketing.
This article breaks down what U.S. merchants actually pay, why they pay it, what’s changing in 2025, and how pricing models like flat rate, interchange-plus, and tiered really compare.
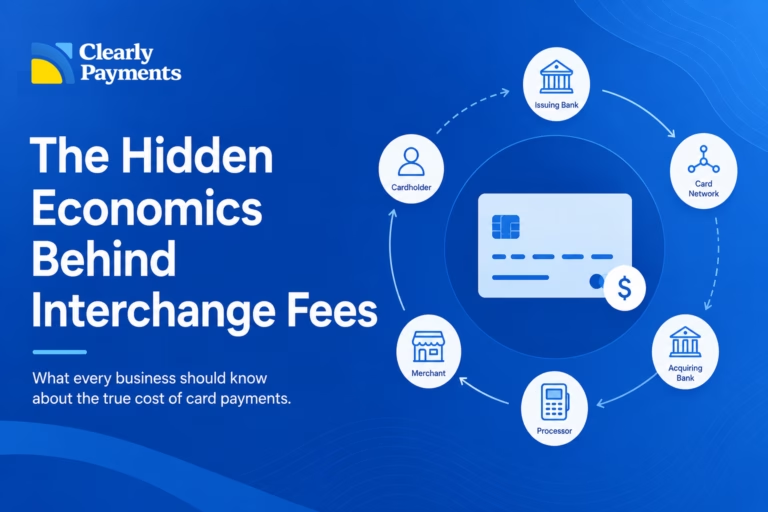
When you accept a card, several parties touch the transaction in a fraction of a second:
Your processing cost is made of three main layers:
The interchange fee is the fee paid to the cardholder’s bank. It’s set by the card networks and is the single biggest cost in most transactions. In 2025, U.S. interchange generally ranges from about 0.5% on low-cost regulated debit up to well over 2% for certain premium credit cards, plus a per-transaction fee.
Example: Visa publishes hundreds of interchange categories. A basic consumer credit card used in-person at a retail store might be ~1.5%–1.7% + $0.10. A high-end “Infinite/World Elite” rewards card at a restaurant can push ~2.6%.
For debit cards issued by large U.S. banks (over $10B in assets), the Fed limits interchange to a cap. Today, that cap is effectively ~$0.21 + 0.05% + $0.01 for fraud prevention.
On a $50 debit sale, that cap works out to:
Why it matters: Interchange is mostly not negotiable for a typical merchant. It is set centrally by networks, and in practice, merchants pay it.
These are fees from the card networks themselves (Visa, Mastercard, etc.) paid on every transaction. They’re usually around 0.13% to 0.15%. You can think of this as “the toll to use the rails.”
This is what your payment processor (like Clearly Payments) charges to operate your account: authorization, fraud tools, chargeback handling, reporting, settlement, PCI compliance support, etc.
The markup can range from ~0.20% for high-volume, low-risk merchants all the way up to 1.0%+ for higher-risk categories, plus fixed per-transaction fees.
When people say “I pay 2.9% + 30¢,” that bundled price includes interchange, network fees, and processor markup combined.
There is a difference in fees and structure between credit cards and debit cards.
Most U.S. merchants pay somewhere between 2.5% and 3.5% per transaction all-in for standard consumer credit cards in 2025.
Smaller merchants (under ~$1M annual card volume) tend to be toward the high end of that range. They have less negotiating power and typically get “flat” or “tiered” pricing from aggregators or legacy processors. Effective rates of 3.2%–4.0% are not unusual once you include statement fees, PCI “non-compliance” fees, chargeback handling fees, etc.
Larger merchants (>$10M annual volume) often negotiate. It’s common to see effective blended rates closer to 1.5%–2.0% because:
Card type matters a lot:
Debit is usually cheaper than credit in the U.S., especially when the card is issued by a large bank and the transaction is in-person with PIN.
Thanks to Regulation II (the “Durbin Amendment”), those large issuers are capped at $0.21 + 0.05% + $0.01.
Result: It’s very common to see effective debit costs below 1%, sometimes well below, for an average ticket like $30–$60.
However:
In practice, most merchants still quote a single blended rate to themselves (“I pay 2.9% + $0.30”) and don’t see the cheaper debit economics unless they’re on an interchange-plus style program where debit savings actually pass through.
Online / card-not-present (CNP) transactions almost always cost more than the same card used in person.
Why?
Result: It’s normal for ecommerce and invoice-pay merchants in the U.S. to see 3.0%+ effective rates, especially if they’re small and using a simple “flat” processor.
This is also why many merchants now steer customers toward ACH/bank transfer or “Pay by bank” at checkout. Bank transfer options often run 1.0%–2.0% or even a fixed low fee per transaction, versus 3%+ for cards.
Payment processing fees are under more scrutiny in 2025 than at any point since the original U.S. debit cap in 2011.
Key trends:
1. Interchange pressure and lawsuits
U.S. merchants have argued for years that swipe fees are too high and largely non-negotiable. Visa and Mastercard reached a multibillion-dollar settlement with merchants that will, among other things, lower and cap certain credit card fees for roughly 3–5 years and let merchants steer customers toward cheaper payment types more easily. The settlement is projected to save U.S. businesses tens of billions of dollars over a five-year window.
This is a big deal for smaller merchants, who historically had almost no leverage.
Practical effect for merchants:
2. Debit fee reform
The Federal Reserve has proposed tightening the regulated debit cap again, targeting a lower base fee and requiring periodic updates every two years. The idea is to align caps with the actual cost to issue debit cards, which the Fed says has gone down.
If finalized, that would further push debit costs down for merchants, especially on small tickets (coffee, QSR, convenience).
3. State-level and federal proposals
Lawmakers continue to push bills like the Credit Card Competition Act and state-level interchange rules. Some proposals would block networks from charging interchange on sales tax and tips, which would directly cut merchant costs in restaurants and service businesses, but also hit bank revenue.
Banks argue that cutting interchange will mean weaker card rewards and more account fees for consumers. Merchants argue they’re already funding those rewards through high swipe fees. Both sides are lobbying heavily.
4. Shift to premium rewards cards
Consumers love high-end rewards (cash back, travel points). Those cards tend to carry higher interchange fees to fund those perks. That shift in consumer behavior, people pulling out their “platinum travel card” instead of a plain debit card, keeps average merchant costs elevated even as regulators try to cap certain categories.
5. Alternative payment rails
Merchants are quietly steering toward cheaper rails: ACH pay-by-bank buttons at checkout, “cash discount” programs at gas pumps, buy-now-pay-later options with negotiated merchant fees, private wallets inside apps, and even store-branded debit. Many of those methods have effective fees closer to 1%–2%, which undercuts a 3%+ online card transaction.
Bottom line on trends:
The way your processor bills you can make a major difference in your overall cost. In the U.S., four main payment pricing models dominate the market.
1. Flat-Rate (Blended)
| Feature | Description |
|---|---|
| How it works | A single rate (e.g., 2.9% + 30¢) applies to all card types and brands. |
| Pros | • Simple and predictable • Easy for small businesses and online checkouts • No complicated statements |
| Cons | • No benefit from low-cost debit cards • Can be expensive as volume grows |
| Best for | Small or seasonal merchants processing under $250K–$500K per year |
2. Interchange-Plus (Cost-Plus)
| Feature | Description |
|---|---|
| How it works | You pay the actual interchange rate (set by the card network) plus a small markup (e.g., 0.20% + 10¢). |
| Pros | • Transparent: you see true costs • Rewards merchants when customers use cheaper debit cards • Scales efficiently with growth |
| Cons | • More complex statements • Some processors add minor monthly or compliance fees |
| Best for | Established or growing merchants seeking cost savings and transparency |
3. Tiered Pricing
| Feature | Description |
|---|---|
| How it works | Transactions fall into categories: “Qualified” (~1.79%), “Mid-Qualified” (~2.49%), “Non-Qualified” (~3.49% + 20¢). |
| Pros | • Appears straightforward at first • Common among legacy processors |
| Cons | • Poor transparency: few transactions truly “qualify” • Easy for providers to reclassify sales into higher-cost tiers |
| Best for | Older accounts; usually worth switching away from this model |
4. Subscription or Membership + Pass-Through
| Feature | Description |
|---|---|
| How it works | You pay a flat monthly fee (e.g., $99) + interchange at cost + a small per-transaction fee (e.g., 8¢). |
| Pros | • Lowest total cost for high-volume businesses • Simple “wholesale” pricing |
| Cons | • May include minimum volume or annual contract • Monthly fee can be inefficient for low-volume or seasonal merchants |
| Best for | High-volume merchants or those with consistent processing activity |
The payment processing model that is cheapest depends on your profile:
Here are the practical levers U.S. merchants are using in 2025:
Clearly Payments can review your processing setup, pricing or payment technology.
Talk to Clearly →
If your business accepts payments from other businesses, government agencies, or large organizations, you may be paying more in credit card processing fees than…
Spoiler: Processing rates are only one piece of the puzzle. Many businesses choose a payment processor based on a simple comparison: 2.9% + 30¢…
When a customer taps, inserts, or enters a credit card online, the transaction appears almost instantaneous. A receipt is generated, funds begin moving, and…