What Are Level 2 and Level 3 Interchange Programs?
If your business accepts payments from other businesses, government agencies, or large organizations, you may be paying more in credit card processing fees than…
A card payment gives a business two different answers at two different times: whether the sale is approved, and when the money reaches its bank account. Understanding that distinction makes payment processing much easier to follow.
Payment processing is the work of securely passing payment information, obtaining a decision, and arranging the transfer of money. This guide explains the card-payment journey, the fees a business may pay, and the questions worth asking before choosing a provider. The principles apply to merchants in Canada and the United States, although network rules, debit systems and commercial terms differ.
The merchant’s view is straightforward: the customer pays, the payment is sent for approval, the result comes back, and the business receives funding later. Here is what happens between those points in a typical online-authorized card transaction.
Authorization, clearing, settlement and merchant funding are connected, but they are not the same event. The U.S. Treasury’s explanation of card processing describes authorization, clearing and settlement as distinct activities. A faster approval does not necessarily mean a faster bank deposit.
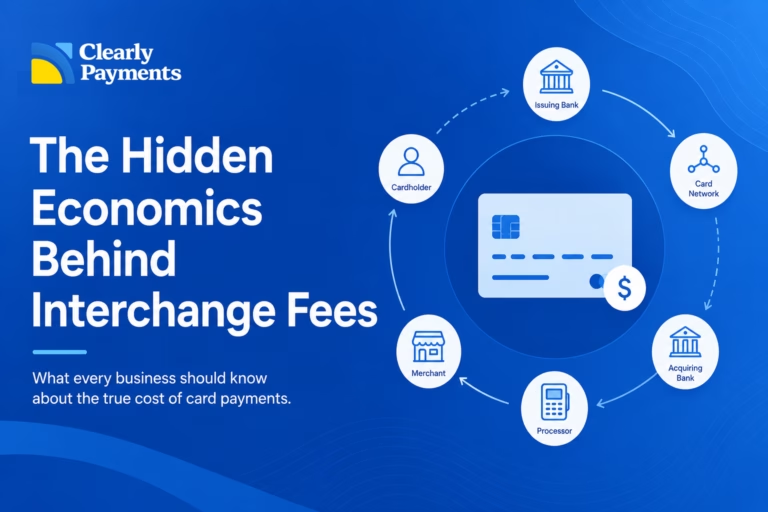
You may deal with one payment company even though several participants help complete the transaction. These are the roles that matter most to a merchant:
A processor and an acquiring bank are not simply two names for the same role, even when one commercial provider supplies both services. For a merchant, the practical questions are who handles the account, who provides support, who manages disputes and who pays out the funds. The payment glossary explains additional terminology.
A merchant account is an arrangement that enables a business to accept card payments through an acquirer. It is connected to the business’s payment acceptance and settlement activity. It is not the same as the everyday bank account where the business receives its deposits.
In a traditional merchant-account arrangement, the business is assessed and set up for acquiring services, often through a payment provider. In a payment-facilitator or aggregated model, a provider enables participating merchants to accept payments under its relationship with an acquirer. Onboarding, account controls, funding and support depend on the arrangement. Visa’s overview of payment facilitators explains how these providers connect merchants to an acquirer.
An integrated payment provider combines payments with software, such as a retail system or booking platform. That describes how the service is delivered, not a separate banking role. It may use either of the account models above. Compare the actual agreement and service rather than assuming one label guarantees better pricing, stability or support.
In-person payments normally use a card reader or payment terminal. A POS system does more than take payment: it can also manage sales, products and business operations. A terminal is the device that accepts the payment, although the two can be combined.
Online and remote payments use similar approval and settlement processes with different ways of capturing payment details. An ecommerce checkout lets customers enter their own details. A virtual terminal lets staff enter an authorized phone or mail order in a browser. A payment-enabled invoice can direct a customer to an online payment page.
Mobile and recurring payments describe different uses of the same infrastructure. A mobile wallet may be used at a terminal or online; a merchant can also accept payments using a mobile device. Recurring billing initiates later payments under the customer’s agreement, commonly using a token or stored payment profile. Each later payment can still be declined.
The channel affects security requirements, fraud exposure and pricing. Card-present and card-not-present transactions do not necessarily qualify for the same fees, even when the customer uses the same card.
A merchant’s total cost can include transaction charges and fees that are billed separately. Some providers combine several components into one price; others show them individually. There is no universal processing rate that applies to every business.
For a typical Visa or Mastercard transaction, interchange is a fee paid by the acquiring side to the cardholder’s issuer. It helps form the underlying cost of accepting the card, but it is not the merchant’s complete processing charge. Visa explains this transfer between acquirers and issuers.
Applicable schedules and qualification rules can vary by network, country, card product, transaction method, merchant category and other conditions. A rewards card, business card, online payment or cross-border transaction may have a different cost. Merchants negotiate their provider’s commercial pricing, rather than an individual card network’s published interchange schedule. See the dedicated Canada interchange-rate reference or U.S. interchange-rate reference for more detail.
Not every account has every fee. Ask what is included, what is passed through at cost, what carries a markup and what can change. A provider’s pricing decisions extend beyond a single advertised transaction markup.
A pricing model describes how charges are packaged. It does not, by itself, establish which quote will cost less for your business.
| Model | How it works | What to examine |
|---|---|---|
| Interchange-plus | Underlying interchange is separated from an agreed provider markup. Network fees may be itemized separately. | Check the markup, treatment of network fees, additional account charges and how clearly the statement supports reconciliation. |
| Flat-rate | A stated transaction price covers a defined class of payments. Different channels or card types may have different flat rates. | Check which transactions qualify, cross-border or other exceptions, and monthly or software fees outside the quoted rate. |
| Tiered or bundled | Transactions are grouped into pricing categories, or costs are combined in a package. | Ask how transactions qualify, what triggers a higher tier, and whether the full cost can be reconciled to your transaction mix. |
| Subscription or membership-style | A recurring service charge is combined with transaction charges, sometimes with underlying costs passed through separately. | Compare the subscription, per-transaction fees, included services and any limits against your actual volume and average sale. |
Separating underlying costs from markup can make a quote easier to audit. A bundled price can be simpler to forecast. Neither benefit removes the need to compare the full fee schedule and your own payment mix. A low headline rate can exclude charges that materially affect the final bill.
A useful starting point is your effective processing rate: total payment-processing fees for a period divided by the corresponding processed sales, multiplied by 100. Use the same period and include all relevant processing charges, even if some arrive on a separate invoice.
For an arithmetic example, $260 in fees on $10,000 in processed sales equals 2.6%. This is an illustration, not a quoted or typical rate. Software and equipment costs may need a separate comparison, especially if they provide functions beyond payments.
Average sale size matters because a fixed transaction fee has a larger percentage impact on a small purchase. Card type, debit versus credit mix, online versus in-person sales, cross-border activity and qualification also affect the result. Two businesses with the same sales volume can therefore have different costs.
Ask prospective providers to price the same sample of transactions and identify every assumption. Compare expected annual costs, not just the percentage on the first page of the proposal.
Encryption protects payment information by making it unreadable without the appropriate key. Tokenization substitutes a reference for sensitive card details so they do not need to be reused throughout the merchant’s systems. These technologies serve different purposes and must be implemented correctly.
Authentication checks evidence that the person paying is entitled to use the payment method. A PIN, a device verification step or an online authentication service may contribute to that check. Authorization is the separate decision about allowing the transaction. EMV 3-D Secure supports authentication for ecommerce payments; it does not guarantee that every payment is legitimate or approved.
PCI DSS sets requirements for protecting payment account data. Using a compliant payment provider or hosted checkout can reduce the systems and responsibilities within a merchant’s scope, but it does not automatically remove the merchant’s obligations. The PCI Security Standards Council explains merchants’ responsibilities when outsourcing processing. Confirm the required validation and the division of responsibilities with your provider.
Fraud controls can include address checks, transaction limits, risk screening and manual review. Choose controls appropriate to the sales channel and consider their effect on legitimate customers as well as fraud.
A chargeback is a disputed payment that can be reversed through the card system. Approval does not eliminate that possibility. Clear descriptions, customer communication, delivery records and timely responses help a business manage disputes, but no single technology prevents every chargeback. Ask who handles notifications, what evidence is required and which fees apply.
Describe your monthly volume, average sale, in-person and online mix, recurring billing and any phone orders. Check terminal requirements, ecommerce compatibility and integration with your existing software. Confirm that refunds, voids, receipts, recurring schedules and reporting work in the way your team needs.
Ask about submission cut-offs, funding schedules, weekends, holds and reserves. Establish whether fees are deducted from each deposit or billed separately, how refunds affect payouts and how deposits can be matched to sales. Network settlement and your funding schedule are related, but they are not interchangeable promises.
Request a complete fee schedule, a sample statement and an explanation of rate changes. Review contract length, renewals, cancellation terms, equipment ownership or leases, and data portability. A seemingly inexpensive payment rate may come with software commitments or exit costs that change the decision.
Confirm support hours, escalation routes, dispute handling and access to transaction records. If you sell internationally, distinguish accepting a foreign-issued card from charging in another currency and receiving settlement in that currency. Verify supported countries, currencies, conversion charges and cross-border fees rather than assuming they are included.
The right choice balances cost, reliable operations, usable technology and support. Understanding where approvals, fees and funding come from gives you a much stronger basis for that decision than choosing the lowest advertised rate alone.
If your business accepts payments from other businesses, government agencies, or large organizations, you may be paying more in credit card processing fees than…
Spoiler: Processing rates are only one piece of the puzzle. Many businesses choose a payment processor based on a simple comparison: 2.9% + 30¢…
When a customer taps, inserts, or enters a credit card online, the transaction appears almost instantaneous. A receipt is generated, funds begin moving, and…