How Long Do Credit Card Payments Take to Settle?
Credit card payments typically take 1–3 business days to settle, although some transactions can settle as quickly as the next business day. The exact…
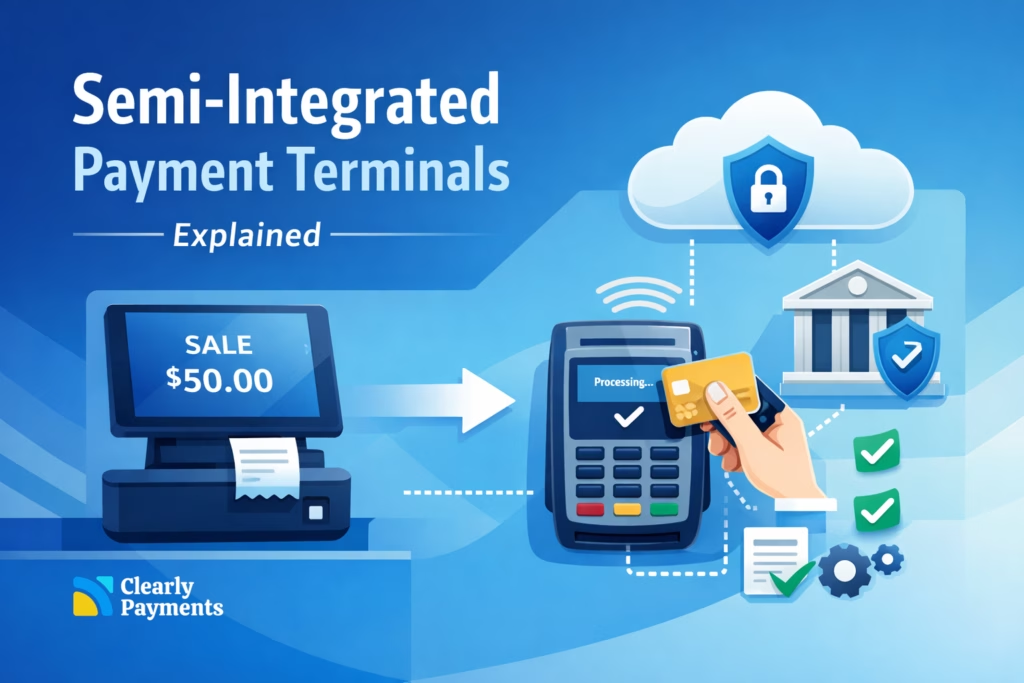
Accepting card payments in person should not force software vendors (SaaS, etc) and merchants to take on unnecessary security risk or compliance work. Semi-integrated payment terminals are designed to solve that problem. They let software vendors and merchants keep a smooth checkout experience while removing sensitive card data from their POS systems.
This article explains what semi-integrated payment terminals are, how they work, and why more merchants are choosing them over fully integrated terminals.
A semi-integrated payment terminal is a card terminal that processes all cardholder data independently from the point-of-sale system.
The POS sends only the transaction amount and basic instructions. The terminal handles the card interaction, encryption, and communication with the processor. The POS never touches card numbers, CVV, or magnetic stripe data.
In practical terms:
This architecture dramatically reduces security exposure while keeping payments fast and familiar for staff and customers.
Semi-integrated payment terminals sit within a fast-growing point-of-sale market. The global POS terminal market is projected to reach over US$200 billion by the early 2030s, growing at roughly 8–10 % annually, driven by contactless payments, mobile wallets, and software-led commerce.
Industries where semi-integrated terminals are widely used:
| Industry | Typical Use Cases |
|---|---|
| Retail and franchises | Multi-location checkout, consistent terminal deployments |
| Restaurants and hospitality | High-volume in-person payments, tipping |
| Healthcare and dental | Regulated environments, front-desk payments |
| Service businesses | Salons, auto repair, professional services |
| SaaS and vertical POS | Embedded payments for merchant customers |
Understanding the difference is helps you plan for both compliance and long-term stability.
| Feature | Integrated Terminal | Semi-Integrated Terminal |
|---|---|---|
| POS handles card data | Yes | No |
| PCI scope | Large | Minimal |
| Breach impact | High | Limited |
| Implementation effort | Heavy | Moderate |
| Ongoing maintenance | Complex | Simpler |
| Best fit | Custom enterprise builds | Most merchants and SaaS |
Integrated terminals require the POS to directly interface with card data flows. This increases PCI requirements, testing, and risk.
Semi-integrated terminals separate responsibilities. The terminal is purpose-built to secure card data, while the POS focuses on sales, inventory, and reporting.
Software vendors and merchants are not switching because semi-integrated terminals are trendy. They are switching because they solve real operational problems.
Reduced PCI Scope: When card data never enters your POS, your PCI obligations drop significantly. This often means fewer controls, less documentation, and lower audit costs.
Lower Breach Risk: If a POS system is compromised, attackers cannot access card numbers because the terminal processes them independently.
Faster Deployment: Semi-integrated setups are quicker to roll out across multiple locations, especially for franchises and growing chains.
Easier Processor Changes: Because the POS is not tightly coupled to a single processor, merchants gain flexibility if pricing or service needs change.
PCI DSS requirements have become more detailed and demanding, especially under newer versions of the standard. Software vendors (SaaS, etc) and merchants using integrated terminals often underestimate the long-term effort required to maintain compliance.
With semi-integrated terminals:
This matters not just for enterprise merchants, but also for small and mid-sized businesses that do not have dedicated security teams.
Semi-integrated terminals are a strong fit for most in-person payment environments, including:
If your business values security, scalability, and predictable compliance costs, semi-integration is usually the right choice.
Clearly Payments supports semi-integrated terminal architectures designed for modern merchants and software platforms.
With Clearly Payments:
This approach allows merchants to focus on running their business while payments operate reliably in the background.
Is semi-integrated slower than integrated payments?
No. In most environments, performance is comparable and often more stable because the POS is not responsible for card data handling.
Can I still support tips, refunds, and receipts?
Yes. Semi-integrated terminals support tipping, refunds, voids, and digital or printed receipts.
Does this work with my existing POS?
Most modern POS systems support semi-integrated flows or can add them with minimal development.
Is semi-integration more expensive?
Hardware costs are similar. Many merchants save money long-term through lower compliance and support costs.
Semi-integrated payment terminals offer a practical balance between usability and security. They reduce risk, simplify compliance, and scale with your business.
Merchants working with Clearly Payments can deploy semi-integrated terminals quickly and confidently, without re-engineering their POS or increasing liability.
If you are evaluating terminal options or planning a POS upgrade, semi-integrated terminals should be your default starting point.
Clearly Payments can review your processing setup, pricing or payment technology.
Talk to Clearly →
Credit card payments typically take 1–3 business days to settle, although some transactions can settle as quickly as the next business day. The exact…
For many software companies, subscription (SaaS) revenue has traditionally been the primary business model. Customers pay a monthly or annual fee to access the…
Artificial intelligence is rapidly evolving from a passive assistant into an active participant in the economy. Today, AI systems summarize documents, answer questions, generate…