What Are Level 2 and Level 3 Interchange Programs?
If your business accepts payments from other businesses, government agencies, or large organizations, you may be paying more in credit card processing fees than…
Accepting card payments is no longer optional for most businesses. Across North America, electronic payments now represent the majority of transactions, meaning nearly every merchant needs a reliable payment terminal. But while choosing a processor gets most of the attention, how you acquire your payment terminal can quietly become one of the most expensive decisions you make.
Payment terminal leasing is often marketed as simple and affordable, yet data shows it frequently costs merchants far more over time than expected.
Before evaluating leasing, it helps to understand the actual cost of payment hardware. Modern payment terminals are relatively inexpensive compared to most business equipment, which fundamentally changes whether financing makes sense.
Typical costs today:
Because the asset itself is low cost and long lasting, leasing often finances something that does not require financing in the first place.
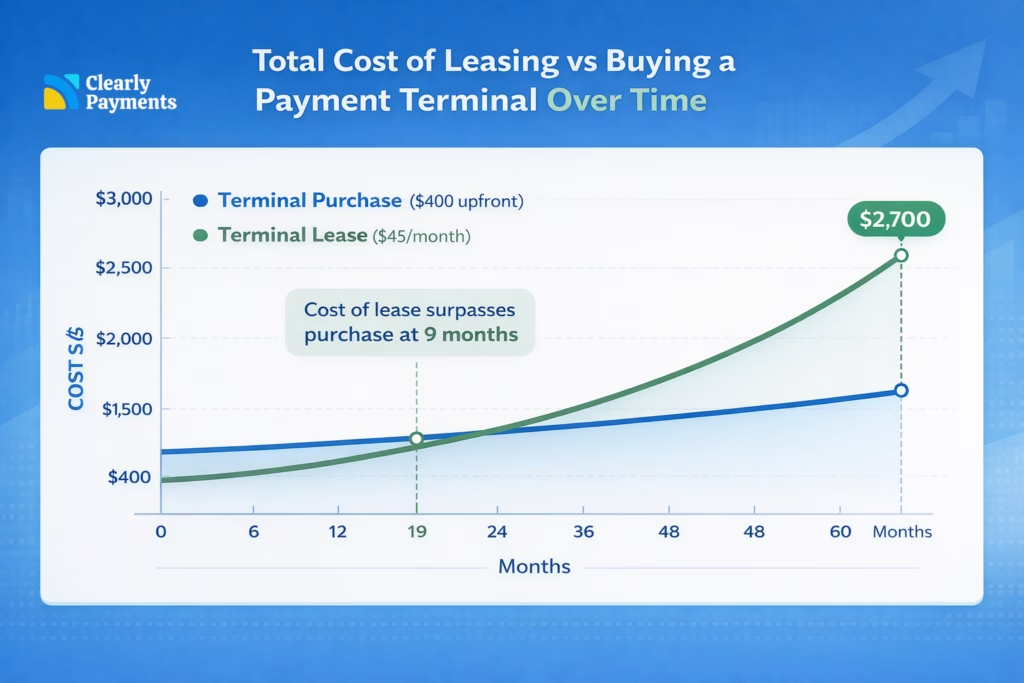
Common lease economics:
In many documented cases, merchants end up paying several multiples of the terminal’s actual value. What feels affordable monthly becomes expensive cumulatively.
Payment technology evolves quickly, and businesses change processors more often than they expect. Leasing contracts, however, are designed for long-term commitment rather than flexibility.
Typical lease restrictions include:
This means a merchant may upgrade their payments provider but still be paying for old hardware months or years later.
Many merchants assume leasing only affects hardware costs, but it can also influence processing freedom. Some leases are bundled directly or indirectly with specific payment providers.
This can create limitations such as:
Processing fees typically range between 1.4% and 3.5% per transaction, so losing flexibility to shop for better pricing can cost far more than the terminal itself over time.
Leasing works well for expensive equipment like vehicles or manufacturing machinery. Payment terminals behave differently because they are inexpensive and depreciate slowly.
Why leasing economics often favor providers:
Equipment lease rates commonly fall between 6% and 16% annually, which is reasonable for large capital assets but disproportionate for small payment devices.
If leasing is frequently more expensive, merchants often ask why it remains common. The answer is simplicity at the point of sale.
Leasing is attractive because it offers:
However, purchased equipment is generally tax deductible just like leased equipment, meaning leasing does not provide a unique tax advantage for most businesses.
Ownership changes the relationship merchants have with their payment infrastructure. Instead of ongoing equipment payments, businesses gain flexibility and predictable costs.
Benefits of buying include:
Because terminals typically remain usable for years, even replacing hardware periodically often costs less than maintaining continuous lease payments.
Payment terminal leasing is not inherently wrong, but data shows it is frequently one of the most expensive ways to acquire low-cost equipment. Small monthly payments can hide financing costs, long commitments, and reduced flexibility that increase operating expenses over time.
Before signing any agreement, merchants should focus on total cost rather than monthly price:
For equipment that costs only a few hundred dollars and sits at the center of daily revenue, ownership often provides the clearest and most economical path forward.
Clearly Payments can review your processing setup, pricing or payment technology.
Talk to Clearly →
If your business accepts payments from other businesses, government agencies, or large organizations, you may be paying more in credit card processing fees than…
Spoiler: Processing rates are only one piece of the puzzle. Many businesses choose a payment processor based on a simple comparison: 2.9% + 30¢…
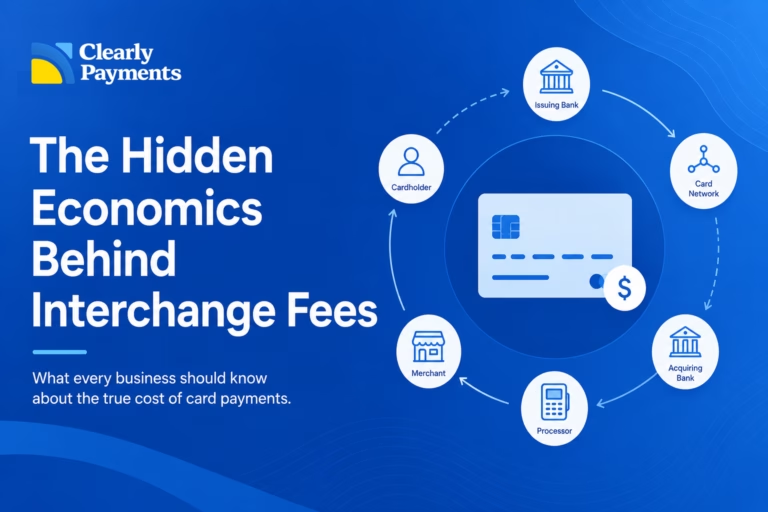
When a customer taps, inserts, or enters a credit card online, the transaction appears almost instantaneous. A receipt is generated, funds begin moving, and…