
Payment Processing for Accountants and Accounting Firms
An accounting firm can finish a tax return on time and still spend weeks collecting the fee. A client forgets a cheque, an invoice gets
Key Takeaways
Portfolio valuation multiples increasingly depend on retention and integration depth, with embedded platforms often achieving 90%+ retention and higher multiples than traditional ISOs.
Merchant churn is one of the most important drivers of long-term portfolio value in payments, yet it is often misunderstood outside the acquiring industry.
At a surface level, churn appears simple: merchants either stay or leave. In reality, payment portfolios behave very differently depending on vertical, merchant size, software dependency, underwriting quality, seasonality, and business model durability.
A restaurant portfolio with 25% annual logo churn may still produce acceptable economics if surviving merchants grow volume over time. Meanwhile, a seemingly stable SaaS portfolio can experience significant revenue churn if a handful of large accounts migrate to embedded payment providers.
In 2026, sophisticated acquirers increasingly evaluate portfolios using:
This report examines how churn behaves across major merchant verticals and why retention quality has become one of the defining metrics in modern payments.
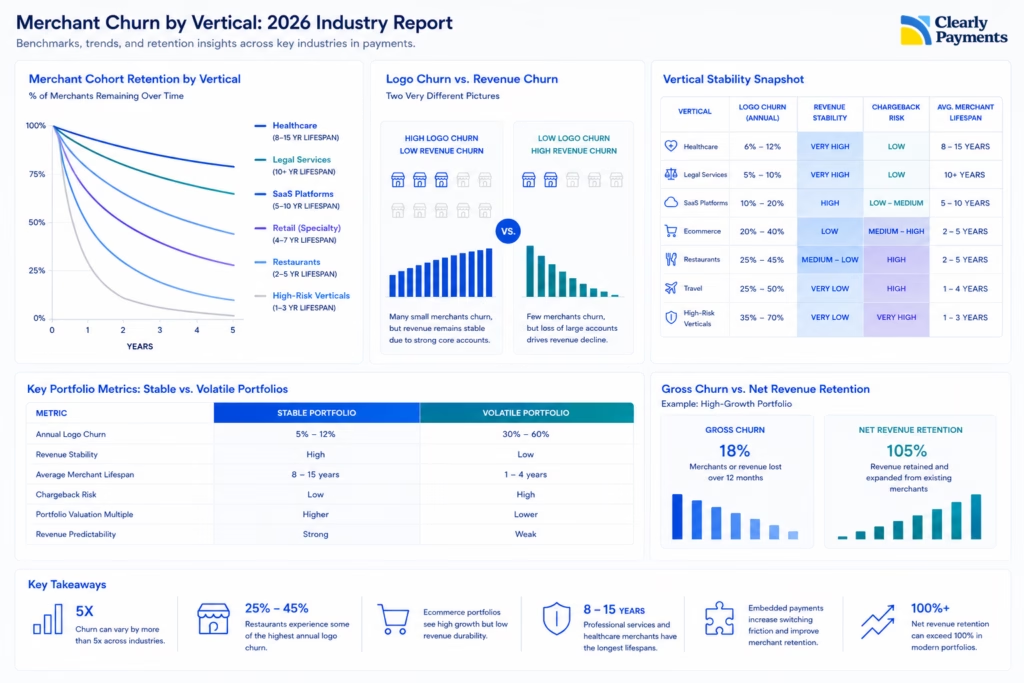
Merchant churn refers to merchants that stop processing with a provider over a given period of time. However, not all churn has the same economic impact.
Processors typically evaluate two separate metrics:
| Metric | Definition | Why It Matters |
|---|---|---|
| Logo Churn | Number of merchants lost | Measures merchant retention and portfolio stability |
| Revenue Churn | Processing volume or revenue lost | Measures economic impact |
| Gross Profit Churn | Net revenue or margin lost | Reflects actual portfolio profitability |
These metrics often diverge significantly.
For example:
This distinction becomes especially important in portfolios with:
Many sophisticated acquirers now care more about revenue durability than merchant count alone.
Payments is fundamentally a lifetime value business. Most processors incur significant upfront acquisition costs, including:
A merchant that churns after 8 months may never recover acquisition costs. By contrast, a low-maintenance professional services merchant processing consistently for 8 to 12 years can generate exceptional lifetime economics.
This is one reason why institutional buyers increasingly prioritize:
over raw onboarding growth.
Merchant churn varies dramatically by industry. The ranges below reflect estimated North American acquiring behavior based on operator experience, portfolio economics, industry disclosures, risk profiles, and embedded payment adoption trends.
| Vertical | Estimated Annual Logo Churn | Revenue Stability | Typical Merchant Lifespan |
|---|---|---|---|
| Legal Services | 5% to 10% | Very High | 10+ years |
| Healthcare & Dental | 6% to 12% | Very High | 8 to 15 years |
| Accounting Firms | 5% to 10% | High | 10+ years |
| Property Management | 8% to 12% | High | 7 to 12 years |
| B2B Services | 8% to 15% | High | 6 to 10 years |
| Auto Repair | 10% to 18% | Medium-High | 5 to 8 years |
| SaaS Platforms | 10% to 20% | High | 5 to 10 years |
| Specialty Retail | 12% to 20% | Medium | 4 to 7 years |
| Contractors/Home Services | 15% to 30% | Medium | 3 to 6 years |
| Ecommerce Brands | 20% to 40% | Low | 2 to 5 years |
| Restaurants | 25% to 45% | Medium-Low | 2 to 5 years |
| Hospitality | 20% to 40% | Low | 2 to 5 years |
| Travel Businesses | 25% to 50% | Very Low | 1 to 4 years |
| Supplements/Nutra | 30% to 60% | Very Low | 1 to 3 years |
| CBD/High-Risk | 35% to 70% | Extremely Volatile | 1 to 3 years |
Importantly, high logo churn does not always imply weak economics. Some fast-growing portfolios generate:
Many of the highest-quality portfolios in payments are made up of businesses that attract very little industry attention. Examples include:
These businesses typically exhibit:
Importantly, these merchants also tend to produce stronger revenue retention alongside lower logo churn. For many acquirers, this creates superior long-term portfolio durability even if growth rates appear slower initially.
Restaurant portfolios have historically experienced elevated churn due to structural industry characteristics. Contributing factors include:
However, restaurant churn analysis has become more nuanced in recent years. A restaurant may technically churn from a processor while remaining active as a merchant through:
As a result, logo churn in restaurants is often much higher than actual industry business closures alone.
Ecommerce portfolios frequently appear attractive because of:
However, ecommerce revenue durability can be highly volatile. Many ecommerce businesses depend heavily on:
As a result:
Sophisticated acquirers increasingly monitor:
rather than simply counting boarded merchants.
One of the largest structural changes in payments is the rise of embedded payments. Historically, merchants selected processors directly. Today, payments increasingly flow through:
This changes churn behavior significantly. Embedded payments often produce:
Once payments become deeply integrated into workflows, switching costs rise materially. This is one reason why software-driven payment companies frequently command premium valuations.
Sophisticated processors increasingly separate:
Gross churn measures merchants or revenue lost. Net churn factors in:
For example:
This dynamic is especially common in:
In some cases, revenue retention can exceed 100% even while logo churn remains elevated.
High-risk portfolios operate under very different retention dynamics.
Verticals such as:
often experience elevated churn because of:
In high-risk acquiring, rapid merchant growth can sometimes conceal weak underlying portfolio quality.
Poorly underwritten portfolios may experience:
As a result, risk-adjusted retention matters significantly more than raw growth.
Sophisticated acquirers increasingly analyze merchant cohorts over time.
Questions include:
A portfolio boarding 1,000 merchants annually can still destroy value if:
This is why experienced operators increasingly focus on:
rather than simply maximizing approvals.
Payment margins continue to compress across much of the industry. As a result, long-term value creation increasingly depends on:
The industry is shifting away from pure transactional processing toward infrastructure and workflow ownership.
In that environment, the highest-value portfolios will likely be those that combine:
Growth still matters.
But in modern payments, durable retention increasingly determines enterprise value.
An accounting firm can finish a tax return on time and still spend weeks collecting the fee. A client forgets a cheque, an invoice gets

Credit card payments typically take 1–3 business days to settle, although some transactions can settle as quickly as the next business day. The exact timing

Businesses in the United States and Canada have hundreds of payment processing providers to choose from, including merchant account providers, acquiring banks, payment facilitators, ISOs,