What Are Level 2 and Level 3 Interchange Programs?
If your business accepts payments from other businesses, government agencies, or large organizations, you may be paying more in credit card processing fees than…
If you’re running a large business and processing a high volume of payments every month, you’re likely wondering if there’s room to reduce your payment processing fees. The short answer is yes, large merchants can negotiate custom payment processing rates. The more complex answer is that all merchants can negotiate payment processing rates, however large merchants just have a more negotiating power.
In this post, we’ll explain how payment processing fees work, why high-volume merchants have more leverage, and what kind of rates you might be able to negotiate.
When a customer pays with a credit or debit card, a few parties get a cut of the transaction. Here’s a simple breakdown:
The first three fees — interchange and assessments and acquirer — are generally fixed by the card networks and banks. But the processor markup is negotiable.
Now, if you are a extremely large merchant with billions of dollars per year, you may have the ability to work directly with credit card networks to get better rates.
High-volume merchants (typically processing $5 million to $250 million per year) are attractive to payment processors because they bring in consistent revenue. If your business fits that profile, you have more negotiating power.
Here’s why processors are open to giving lower rates to high-volume businesses:
Lower risk: Larger, established businesses are usually seen as more stable.
Economies of scale: The cost of servicing a high-volume merchant is often lower on a per-transaction basis.
Long-term value: A large merchant represents a significant, long-term relationship for a processor.
While small businesses might pay effective rates between 2.5% to 3.5% on credit card transactions, high-volume merchants often pay far less. With the right setup, large businesses can get rates in the 1.65% to 2.10% range, depending on how payments are taken.
Some of our large customers at Clearly Payments are paying 30% to 50% less than what they were paying before switching.
If you’re a high-volume merchant and want to negotiate better rates, here’s what to do:
Know your numbers: Understand your average monthly processing volume, average transaction size, and the types of cards you accept.
Request Interchange Plus Pricing: Interchange Plus is the most transparent and fair pricing structure, especially for large merchants.
Compare processors: Don’t settle for the first quote. Some processors offer volume discounts or enterprise pricing structures.
Ask for custom rates: If you process a lot, don’t accept standard rates. You should be paying less.
Watch out for hidden fees: Some processors offer a low rate but add in monthly fees, minimums, and PCI compliance charges. Always look at the full picture.
Getting the ideal rates often come down to preparation. Before you approach a payment processor (or renegotiate with your current one), it helps to have:
A recent 1–3 months of statements: Processors use this to evaluate volume, card mix, and fees.
Details on your business model: Processors consider industry type, chargeback history, and transaction methods (in-person, online, phone).
Your current effective rate: If you’re not sure what you’re paying after all fees, we can help you calculate it.
Understanding a few key terms can give you a serious edge:
Interchange Plus: A transparent pricing model where you pay the actual interchange fee plus a small markup.
Effective Rate: The total processing fees divided by total sales — gives you a true apples-to-apples comparison.
Tiered Pricing: A less transparent model that often overcharges for certain transactions.
PCI Compliance Fee: A fee for security compliance — often negotiable or avoidable.
Batch Fee: A small daily fee when you close out your terminal — may be waived for large merchants.
At Clearly Payments, we specialize in helping high-volume merchants lower their costs and simplify their payment systems. We don’t believe in locking you into long contracts or hiding fees. Our mission is to offer transparent, custom pricing that actually benefits your business.
If you process between $5 million to $250 million per year in payments, we’d love to review your current setup and show you where you can save — no pressure, just honest advice.
Clearly Payments can review your processing setup, pricing or payment technology.
Talk to Clearly →
If your business accepts payments from other businesses, government agencies, or large organizations, you may be paying more in credit card processing fees than…
Spoiler: Processing rates are only one piece of the puzzle. Many businesses choose a payment processor based on a simple comparison: 2.9% + 30¢…
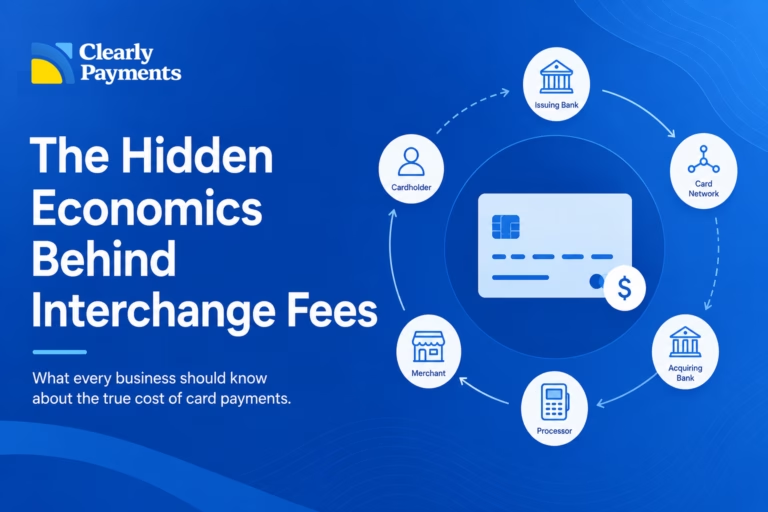
When a customer taps, inserts, or enters a credit card online, the transaction appears almost instantaneous. A receipt is generated, funds begin moving, and…