What Are Level 2 and Level 3 Interchange Programs?
If your business accepts payments from other businesses, government agencies, or large organizations, you may be paying more in credit card processing fees than…
Credit card processing fees can seem confusing and overwhelming for many businesses. Whether you’re a small retailer, a restaurant owner, or run an online store, it’s important to understand how much you should pay and what you’re paying for.
In this article, we’ll break down credit card processing costs, explain the math behind them, and give you benchmarks so you know whether you’re getting a good deal.
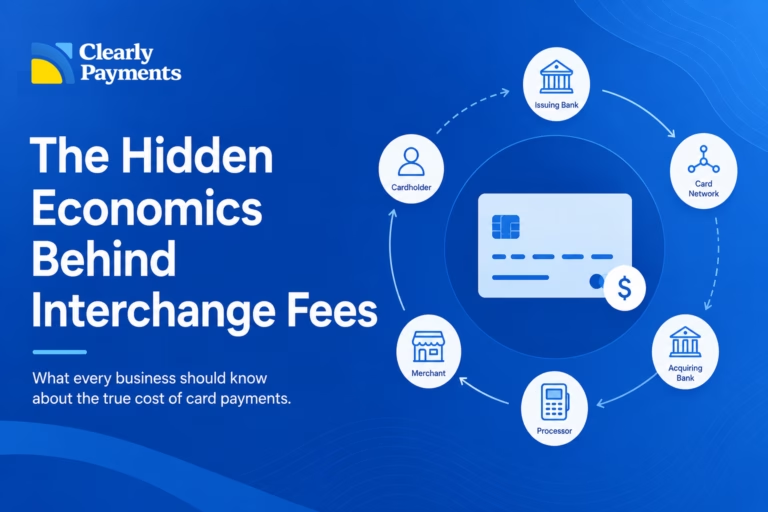
Every time a customer taps, swipes, or enters their credit card number, a chain of behind-the-scenes steps kicks in to move money from their bank account to yours. While this process happens in seconds, it involves multiple companies, each taking a small cut.
Credit card processing fees are made up of a few main parts, and they’re usually charged as a percentage of each sale, plus sometimes a small fixed fee. A transaction goes through several steps:
The card is authorized.
The payment is routed through the card network (Visa, Mastercard, etc.).
The money is deposited in your business bank account (minus fees).
For this service, several parties charge fees:
Issuing Bank (the customer’s bank)
Card Network (Visa, Mastercard, Amex, etc.)
Acquirer / Processor / ISO (your payment processor or merchant services provider)
These fees fall into three main categories:
| Fee Type | Who Gets It | Typical Range |
|---|---|---|
| Interchange fee | Issuing Bank | 1.3% – 2.5% |
| Assessment | Card Network | ~0.13% – 0.15% |
| Processor Fee | Your payment provider | Varies (flat fee or % based) |
In general, most merchants in the U.S.A. and Canada pay between 2.0% and 3.2% in total processing fees for credit card transactions. Here’s a breakdown of credit card processing fees by country. Here’s a typical breakdown:
| Component | Percentage (Estimate) |
|---|---|
| Interchange Fee | 1.80% |
| Assessment Fee | 0.14% |
| Processor Markup | 0.40% |
| Total | 2.34% |
So, for a $100 sale, a merchant might pay about $2.34 in total fees.
Let’s say you run a coffee shop that does $40,000 per month in credit card sales. If your total average processing rate is 2.5%, here’s how much you pay per month:
$40,000 × 2.5% = $1,000 per month
That’s $12,000 per year in fees. If you can lower your rate to 2.2%, your cost drops:
$40,000 × 2.2% = $880 per month
That’s $10,560 per year and a savings of $1,440 per year, just by lowering your rate 0.3 percentage points.
There are different pricing models for credit card processing:
You pay one fixed rate for all transactions. Example: 2.9% + 30¢ (popular with companies like Square or Stripe). Simple but can be more expensive.
You pay the exact interchange rate + a fixed markup. Example: Interchange + 0.30% + 10¢. This model is transparent and often cheaper for growing businesses.
Rates are divided into tiers: “qualified,” “mid-qualified,” and “non-qualified.” This structure is often confusing and may hide high fees, so we recommend avoiding tiered pricing.
Not all businesses pay the same credit card processing rates — and it’s not just about which provider you choose. Your actual costs are influenced by a range of factors that payment processors use to assess risk, transaction complexity, and profitability.
Things like how you accept payments, what type of cards your customers use, and even your industry can all impact your final rate. Understanding these variables gives you more control and helps you make better decisions when negotiating with providers or reviewing statements.
Here’s a breakdown of the key factors that can push your fees up — or help bring them down.
| Factor | Effect on Cost |
|---|---|
| Type of Card | Rewards and corporate cards have higher fees |
| Transaction Method | In-person (chip) is cheaper than keyed-in |
| Business Type (MCC Code) | Some industries have higher risk and higher fees |
| Average Ticket Size | Small-ticket businesses may be hit harder by per-transaction fees |
| Monthly Volume | Higher volume may lead to lower rates |
Credit card processing costs aren’t one-size-fits-all. Different industries face different levels of risk, average ticket sizes, and transaction types — and processors adjust their pricing accordingly. That means a retail store, a restaurant, and an online business can all pay very different rates, even if their sales volumes are similar.
Looking at industry benchmarks helps you understand where your rates stand compared to others in your field. It’s a useful reference point when evaluating your current pricing or negotiating a better deal.
Here’s what businesses in various industries typically pay in processing fees.
| Industry | Average Rate (%) |
|---|---|
| Retail (in-person) | 1.95% – 2.50% |
| eCommerce | 2.30% – 3.10% |
| Restaurants | 2.00% – 2.70% |
| Professional Services | 2.00% – 2.70% |
| High-Risk Industries | 3.00% – 8.00% |
Credit card fees can quietly eat into your profits — but the good news is, many merchants are overpaying and don’t even realize it. With a few smart moves, you can reduce your rates and keep more of what you earn. Even a small decrease in fees can add up to thousands in annual savings.
Here are some effective ways to lower your credit card processing costs:
Don’t rely on a single quote. Processing rates can vary significantly across providers, especially between banks, legacy processors, and modern platforms. Look at the effective rate (your total fees divided by total sales), not just the headline rate.
Tip: Providers like Clearly Payments offer free rate reviews and transparent pricing models to help you benchmark your current setup.
Interchange-plus passes the true cost of each transaction (set by the card networks) directly to you, with a fixed markup. This model is more transparent and often more affordable than tiered or flat-rate pricing — especially for growing or high-volume businesses.
If you have consistent volume, low refund rates, or have been with your provider for a while, you may be eligible for better pricing. Ask for lower processing rates, and check if ancillary fees can be waived or reduced.
Leasing credit card terminals can lock you into long contracts and inflated fees. If possible, buy your terminal outright — or work with providers like Clearly Payments that offer equipment at cost or no monthly rental.
Read your monthly statements carefully. Look for fees like:
PCI non-compliance charges
Statement fees
Batch fees
Monthly minimums
Providers like Clearly Payments are known for zero hidden fees and fully transparent billing — which can save you money over time.
Being PCI compliant can reduce certain fees and protect your business from data breaches. Many processors offer support and tools to help you stay compliant at no extra cost.
For eCommerce or manually entered transactions, enabling AVS helps verify billing information and may reduce your risk profile, potentially lowering your interchange costs.
If your business accepts payments from other businesses, government agencies, or large organizations, you may be paying more in credit card processing fees than…
Spoiler: Processing rates are only one piece of the puzzle. Many businesses choose a payment processor based on a simple comparison: 2.9% + 30¢…
When a customer taps, inserts, or enters a credit card online, the transaction appears almost instantaneous. A receipt is generated, funds begin moving, and…